

W-2 vs. W-9: Key Differences Every Employer Should Know
- Lectura de 6 minutos
- Last Updated: 10/29/2026

Table of Contents
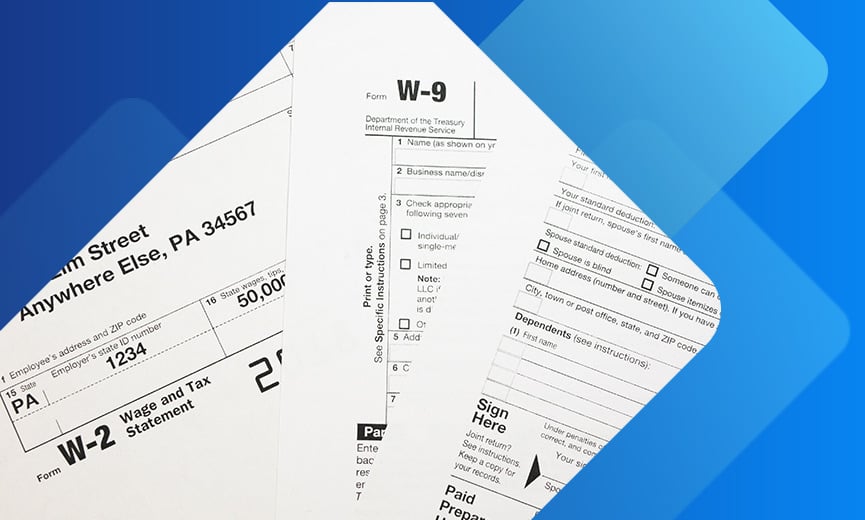
If a new vendor has ever handed you a W-9, or you’ve wondered why your contractors don’t get W-2s, you’re in good company. These two forms get compared all the time, but they aren’t two versions of the same thing. A W-2 is a year-end report you prepare for each employee, showing what you paid them and the taxes you withheld. A W-9 is an intake form a contractor fills out for you before you pay them. It never goes to the IRS. Instead, it gives you the information you need to file a different form, the 1099-NEC, at year-end.
That’s why the choice between them comes down to one decision you make first: is the worker an employee or an independent contractor? An employee works under your direction and control. An independent contractor runs their own business and decides how and when the work gets done. Once you’ve made that call, the right forms and your tax obligations follow.
Whether you’re bringing on your first worker or your fiftieth, getting this right matters. Using the wrong form can be a sign of worker misclassification, which can lead to back taxes, penalties, and benefit obligations. Below, we’ll walk through how each form works, how each one connects to your year-end filings, and how to make the classification decision with confidence.
W-2 vs. W-9 at a Glance: The Key Differences
Because the forms do such different jobs, the clearest way to compare them is by what each one asks of you: who fills it out, what you withhold, and where it goes.
Here’s a comparison at a glance:
| Factor | Form W-2 | Form W-9 |
|---|---|---|
| Worker type | Employees | Independent contractors, freelancers, and vendors |
| Purpose | Reports an employee’s wages and the taxes withheld | Collects a contractor’s taxpayer identification number (TIN) so you can file Form 1099-NEC when required |
| Who completes it | You, the employer, prepare and issue it | The contractor completes it and gives it to you |
| Tax withholding | You withhold federal income tax, Social Security, and Medicare | None, because the contractor pays their own taxes, unless backup withholding applies |
| When you use it | Issued to employees and filed with the Social Security Administration (SSA) by January 31 of the following year (February 1, 2027, for 2026 wages) | Collected before the first payment and kept on file |
| What comes next | The employee uses it to file a personal tax return | Used to prepare Form 1099-NEC when payments reach the annual threshold ($2,000 for 2026) |
| Employer FICA | You pay a matching share of Social Security and Medicare (7.65% combined) | No employer FICA on contractor payments |
A quick note on the last row: FICA, the Federal Insurance Contributions Act tax, is Social Security (6.2%) plus Medicare (1.45%). The Social Security portion applies only up to an annual wage base, which is $184,500 for 2026.
Form W-2: What Employers Need to Know
Form W-2, the Wage and Tax Statement, is the annual form employers generally must provide to employees when applicable wage or tax reporting requirements are met. It reports their total wages for the year and the taxes you withheld, along with details such as retirement plan contributions and certain benefits.
Throughout the year, employers generally withhold federal income tax from employees' wages based on their Form W-4 or applicable IRS withholding rules. Employers also generally withhold Social Security and Medicare taxes from covered wages and pay their own matching share of these taxes. These employer matching obligations generally do not apply to payments made to properly classified independent contractors. Worker classification is therefore an important factor in determining payroll tax obligations.
The W-2 has 20 numbered boxes plus a set of codes for Box 12, and small mistakes are a common reason employers end up filing corrections on Form W-2c, so it pays to double-check names, Social Security numbers, and wage totals before you file.
Form W-9: What Employers Need to Know
The IRS Form W-9, Request for Taxpayer Identification Number and Certification, is completed by the contractor, rather than the business making the payment. It is used to collect a contractor’s taxpayer identification number (TIN) before you pay them. A TIN may be the individual’s Social Security number or the business’s Employer Identification Number (EIN). For step-by-step help, see how to complete a W-9.
Ask for the W-9 before the first payment, not at tax time. It stays in your files as the source data for the 1099-NEC you may need to file at year-end.
What to Check When a W-9 Comes Back
A W-9 only helps you at year-end if the information on it is right. A quick review when it arrives can save you from a rejected 1099-NEC or a backup withholding notice later. Look for:
- A name that matches the TIN. The name on line 1 must match the number in Part I. For a sole proprietor, line 1 should show the owner’s name, with the business name on line 2. For a single-member LLC that’s treated as a disregarded entity, line 1 should show the owner, and the TIN should be the owner’s.
- A checked tax classification. Line 3a tells you what kind of entity you’re paying. This helps you decide whether you’ll need to file a 1099-NEC. For example, payments to C corporations and S corporations generally aren’t reportable, while payments to sole proprietors and most LLCs are.
- A signature and date. The contractor certifies the information under penalty of perjury in Part II. However, the IRS does not require a signature for all payment types. For most nonemployee compensation payments, a correct TIN generally may be provided without a signature unless the payee has previously been notified of an incorrect TIN. Employers should verify whether certification is required under the applicable IRS instructions.
- The current version of the form. The March 2024 revision is the latest. Older W-9s you already have on file don’t need to be replaced just because the form was updated.
If you file information returns, you may also be able to use the IRS TIN Matching program to confirm a contractor’s name and TIN combination before year-end.
If a Contractor Doesn’t Return a W-9
Don’t wait until January to follow up. Make the request part of your onboarding process, and hold off on the first payment until the form is in hand when you can.
If a contractor doesn’t provide a TIN, you must begin backup withholding on payments that are reportable. That means holding back 24% of each payment, depositing it with the IRS, and reporting it on Form 945 and on the contractor’s 1099-NEC. Keep a record of each time you asked for the W-9, since documented requests help show you acted in good faith.
The IRS may also tell you that a name and TIN you reported don’t match its records. This comes through a notice called a CP2100 or CP2100A. When that happens, you generally have 15 business days to send the contractor a “B notice” asking for corrected information. If they don’t respond, you have 30 business days from receiving the IRS notice to start backup withholding.
How Long to Keep a W-9 and How to Store It
The IRS recommends keeping each W-9 for at least four years. Because the form contains a Social Security number or EIN, store it as carefully as you would an employee’s personnel file. Use a locked cabinet or secure digital storage, with access limited to the people who handle payments.
Ask for a new W-9 whenever something on the old one changes, such as a contractor’s name, business structure, or address. Many businesses also refresh W-9s for active vendors every year or two, so their records are current before 1099 season.
When You Don’t Need a W-9
Not every worker or payment calls for a W-9. You generally don’t need one when:
- The worker is an employee. Employees complete a W-4, not a W-9.
- You’re paying a corporation. Payments to corporations generally aren’t reported on a 1099-NEC, with exceptions such as attorney fees. Many businesses still collect a W-9 from every vendor, because it also confirms the vendor’s tax classification.
- You’re paying a tax-exempt organization. These payments generally aren’t reportable either.
- The contractor is outside the U.S. A non-U.S. contractor completes Form W-8BEN (individuals) or Form W-8BEN-E (businesses) instead.
- Payments stay under the reporting threshold. For 2026, you only file a 1099-NEC once payments to a contractor reach $2,000, and that figure will be adjusted for inflation starting in 2027. Collecting the W-9 up front is still smart, since you can’t always know in advance how much you’ll pay over the year.
The Downstream Form Chain: How W-2 and W-9 Connect to What Comes Next
Neither form stands alone. Each one is part of a chain of forms and deadlines, and a missed step early on causes trouble at year-end. The W-4 is the starting point for W-2 compliance, while the W-9 is the starting point for 1099-NEC compliance.
The employee chain (W-4 to W-2):
- The worker is hired as an employee and completes Form W-4 to tell you how much federal income tax to withhold.
- You withhold taxes from every paycheck and deposit them on your IRS deposit schedule.
- You give Form W-2 to the employee by January 31, or the next business day if January 31 falls on a weekend. For 2026 wages, the deadline is February 1, 2027.
- By the same deadline, you file the W-2 copies with the SSA, along with Form W-3, the summary of all your W-2s.
The contractor chain (W-9 to 1099-NEC):
- You engage the contractor and collect Form W-9 before the first payment.
- You track what you pay them across the year.
- If your payments reach the reporting threshold ($2,000 for 2026), you give Form 1099-NEC to the contractor and file it with the IRS by January 31, or the next business day if it falls on a weekend. Our guide walks through how to file 1099-NEC step by step.
- Note: If the W-9 is missing or incorrect, year-end filing gets harder and backup withholding may apply.
Putting It Together: An Example
Say you run a landscaping company. In 2026, you hire a crew leader who works the schedule you set, drives your trucks, uses your equipment, and stays on year-round. You also bring in a bookkeeper who runs her own practice as a sole proprietor, serves several other clients, and bills you $3,500 over the year.
Your crew leader is an employee. He completes a W-4 when he starts, you withhold taxes from every paycheck, and you give him a W-2 by February 1, 2027. Your bookkeeper is an independent contractor. She gives you a W-9 before her first invoice, you track what you pay her, and because her total passes $2,000, you send her a 1099-NEC by the same date. If she had billed you $1,500 instead, you would keep her W-9 on file but wouldn’t need to file a 1099-NEC for 2026.
For the full list of forms you may handle, see our complete guide to employer tax forms.
How to Decide: W-2 or W-9?
Since everything else follows from classification, here’s how the IRS worker classification guidance helps you make that call. It looks at three types of evidence:
- Behavioral Control: Do you control how the work gets done?
- Financial Control: Do you control the business side of the work, such as pay, tools, and expenses?
- Type of Relationship: Are there employee-type benefits, or an expectation that the work continues indefinitely?
No single factor decides it, and a signed contract won’t settle it on its own. The IRS looks at how the relationship actually works day to day. The table shows which way common signs point:
| Sign | Points to a W-2 Employee | Points to a W-9 Contractor |
|---|---|---|
| Schedule and hours | You set them | The worker decides |
| Tools and equipment | You provide them | The worker supplies their own |
| Method of work | You direct how it’s done | The worker decides how it’s done |
| Other clients | Works for you on an ongoing basis | Serves multiple clients |
| Length of engagement | Ongoing | Project-based or time-limited |
For a closer look at each factor, see our guide to independent contractor vs. employee. To compare the year-end forms side by side, see 1099 vs. W-2.
When the Answer Isn’t Clear
If you’re unsure about a worker you already have, you can ask the IRS for a formal determination using Form SS-8 (Determination of Worker Status for Purposes of Federal Employment Taxes and Income Tax Withholding). The IRS won’t rule on proposed arrangements, so for a new engagement, talk with a qualified tax or HR professional before the work begins.
Check your state’s rules as well. Some states, including California, Massachusetts, and New Jersey, use a stricter ABC test that presumes a worker is an employee unless the business can show otherwise. If you operate in more than one state, verify each state’s standard.
The Cost of Getting It Wrong: Worker Misclassification
If you treat an employee as a contractor and the IRS or a state agency reclassifies them, you may owe back employment taxes, interest, and penalties. For unintentional misclassification, the IRS may figure the employee’s share of taxes at reduced rates under Section 3509, though you still owe your full employer share of FICA. The worker may also become eligible for benefits going back in time, such as retirement plan contributions or unemployment insurance. State and federal labor agencies can assess penalties of their own, separate from the IRS.
The best safeguard is simple. At the start of every contractor engagement, write down what you considered and why you concluded the worker is an independent contractor. Those records are your first line of defense in an audit. If you think you may have already misclassified someone, talk with a tax professional about whether IRS relief options, such as Section 530 relief or the Voluntary Classification Settlement Program, may apply.
W-2 vs. W-9 FAQs
-
Does an Independent Contractor Use a W-2 or a W-9?
Does an Independent Contractor Use a W-2 or a W-9?
An independent contractor completes a W-9, not a W-2. The W-9 gives you the contractor’s taxpayer identification number so you can report their payments on Form 1099-NEC once they reach the threshold. W-2s are only for employees, who are paid through your payroll and have taxes withheld from each paycheck.
-
What Happens if an Employer Uses the Wrong Form?
What Happens if an Employer Uses the Wrong Form?
Using the wrong form can be a sign that a worker is misclassified. If a contractor is later reclassified as an employee, you may owe back taxes, interest, and penalties, and the worker may qualify for retroactive benefits. Your best protection is documenting your classification decision at the start of every engagement.
-
When Does a W-9 Require a 1099-NEC?
When Does a W-9 Require a 1099-NEC?
A W-9 leads to a 1099-NEC when you pay a contractor $2,000 or more for services during 2026. The threshold was $600 for payments made before then, and it will be adjusted for inflation each year starting in 2027. You file by January 31 of the following year, or the next business day if January 31 falls on a weekend (February 1, 2027, for 2026 payments). If you applied backup withholding, you report the payments regardless of the amount.
Simplify W-2 and Contractor Management With Paychex
Chasing W-9s, tracking contractor payments, and getting W-2s out on time all land on your desk at the busiest time of year. And the more your workforce mixes employees and contractors, the more there is to keep straight.
Paychex has helped businesses manage payroll and tax compliance for more than 50 years, and today we pay 1 in 11 American private-sector workers. Our payroll and tax services can handle both sides of your workforce. We generate and distribute W-2s for your employees and prepare 1099-NECs for your contractors. We can also automate tax deposits, and our HR advisors can help you evaluate worker classification questions before they turn into audit problems.
Ready to take contractor payments and 1099s off your plate? See how Paychex helps you onboard contractors, pay them your way, and file 1099-NECs on time.
Tags